Posts

Showing posts with the label Income Tax

Taxation of "Salary Income" in India - FY 2022-23

A. Brief of Salary Taxability ​​​​​​​​​Section 17​​ of the Income-tax Act defines the term ‘salary’. Generally, it includes whatever is received by an employee from an employer (current as well as former) in cash, kind or as a facility (perquisite / allowance). It shall be chargeable to Income Tax, considering the following: Due in previous year, whether paid or not (i.e., salary accrued) Paid or allowed in the previous year, though not due or before it became due (i.e., advance salary) Arrears of salary paid or allowed in previous year, if not taxed earlier (i.e., arrears of salary) For advance salary and arrears of salary, the Act has provided relief u/s. 89 for the differential amount of tax –  Click here  to read our detailed article on the same. B. Taxability of Allowances received as a part of salary Allowances are fixed periodic amounts, apart from salary, which are paid by an employer for the purpose of meeting some particular requirements of the employee. E.g...

Income Tax Returns for FY 2021-22 (AY 2022-23)

Dear Readers, Many of you must be aware that the due date of filing Income Tax Returns (“ITR”) for Financial Year 2021-22 (“FY 2021-22”) or say Assessment Year 2022-23 (“AY 2022-23”) for Individual / HUF/ AOP/ BOI, in whose case tax audit is not applicable is approaching and one needs to file the same latest by 31st July, 2022 for timely compliance of the same. However, if the same could not be met due to any reason, one can file the same belatedly by 31st December, 2022. Further, to bring your knowledge, we would like to mention here the repercussions of the case when ITR could not be filed within the original due date i.e., 31st July, 2022.  Penalty u/s. 234F of ₹ 5,000/- if the total income exceeds ₹ 5,00,000/- and in other case it would be ₹ 1,000/- Interest u/s. 234A at the rate of 1% for every month or part of a month on the unpaid tax amount,  comprised in the period commencing on the date immediately following the due date till the date of furnishing ITR So, for your...

Income tax due date extension- FY 2020-21

Image
Please find the below press note released on 11th January 2021:

Relaxation in provisions of section 194A

Image
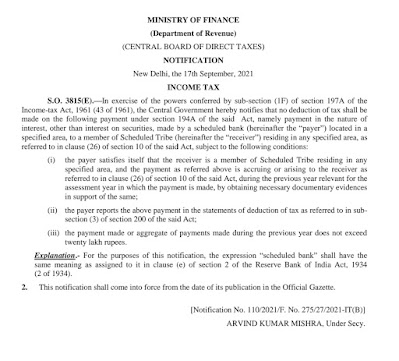
Central Government relaxes provisions of TDS u/s 194A of the Income-tax Act, 1961 in view of section 10(26) of the Act. CBDT Notification No. 110/2021 in S.O. 3815(E) dated 17th September, 2021 issued. Copy of notification:

Further extension of due dates for income tax

Image
On consideration of difficulties reported by the taxpayers in filing of Income Tax Returns(ITRs) & Audit reports for AY 2021-22 under the ITAct, 1961, CBDT further extends the due dates for filing of ITRs & Audit reports for AY 21-22. Circular No.17/2021 dated 09.09.2021 issued. Copy of press release: If you have any query related to the article please reach us via mail:-mrinkblog@gmail.com  Advisory: Information relates to the law prevailing in the year of publication as indicated. The above article is only to enable public to have a quick and an easy understanding. Viewers are advised to ascertain the correct position/prevailing law before relying upon any document.

Income Tax Notification 95/2021: Income-tax (25th Amendment) Rules, 2021 applicable w.e.f. 01/04/2022 - taxability of interest on PF contributions

G.S.R. 604(E) .- In exercise of the powers conferred by the first proviso to clause (11) of section 10 and the first proviso to clause (12) of section 10 read with section 295 of the Income-tax Act, 1961 (43 of 1961), the Central Board of Direct Taxes hereby makes the following rules further to amend the Income-tax Rules, 1962, namely:- 1.  Short title and commencement,- (1) These rules may be called the  Income-tax (25th Amendment) Rules, 2021 . (2) They shall come into force on 01/04/2022. 2. In the Income-tax Rules, 1962, after the rule 9C, the following rule shall be inserted, namely:- 9D. Calculation of taxable interest relating to contribution in a provident fund or recognised provided fund, exceeding specified limit.- (1) For the purposes of the first and second provisos to clauses (11) and (12) of section 10 , income by way of interest accrued during the previous year which is not exempt from inclusion in the total income of a person under the said clauses (here...

Further Extension of certain due dates - Income Tax

Image
On consideration of difficulties reported by taxpayers & other stakeholders in electronic filing of certain Forms under the IT Act,1961, CBDT has further extended the due dates for electronic filing of such Forms. CBDT Circular No.16/2021 dated 29.08.2021 issued. Copy of press release:

CBDT extends date of Vivad se Vishwas

Image
In press release dated 29th August, 2021 the CBDT has extended Date of payment under the Direct Tax Vivad se Vishwas Act, 2020 (without additional amount) to 30th September, 2021. The last date for payment of the amount (with additional amount) remains 31st October, 2021 Copy of press release:

Press release on framing of rules for the amendments made by the Taxation Laws(Amendment) Act, 2021

Image
On 28th August, 2021 press release has been issued by the ministry of finance, wherein the CBDT invites comments on the draft notification for framing of rules for the amendments made by the Taxation Laws(Amendment) Act, 2021, which is in connection to nullify the retrospective taxation. Suggestions can be furnished at ustpl1@nic.in latest by 4th September, 2021. Draft notification is available at below given link: Draft notification Copy of press release is provided hereunder for reference:

Important due dates of Income Tax Compliance_FY 2020-21 (AY 2021-22)

Image
  In today’s scenario, where certain relief/ extensions are being granted by the CBDT regarding reporting/ filing of Income Tax Compliances, it has become somehow difficult to remember the actual due date of the same. One needs to comply with the filing/ reporting requirement within applicable due dates, as failure to which will result into the levy of penalty or interest or both. However, dear readers you don’t have to bother about it, we have made it easy for you to take note of applicable due dates by providing the details in simpler way as follows: Chart for Income tax related due dates for the FY 2020-21 (AY 2021-22) Due date chart- FY 2020-21 (AY 2021-22) Reporting/ Filing requirements Original Due date Extended due date (Note-1) 1. SFT filing- Form No. 61A 31-05-2021 30-06-2021 2. TDS return for 4th Quarter 31-05-2021 30-06-2021 3. Tax Audit Report- Form N...

Extended date for manual filing of form 15CA 15CB

Image
CBDT grants further relaxation in electronic filing of forms 15CA & 15CB in view of difficulties reported by taxpayers in filing of the forms online on incometax.gov.in.  Date for submission of forms in manual format to the authorised dealers is extended to 15th July, 2021. Copy of press release:

Income Tax New functionality-Section 206AB & 206CCA

Image
The Finance Act 2021 has introduced two new sections- Section 206AB & 206CCA, which require to deduct/ colllect tax at higher rate for certain defined class of non-filers of Income Tax Returns of two previous years. The said sections are applicable w.e.f. 01-07-2021 in case where the amount of TDS/ TCS is in excess of Rs.50,000/- Section 206AB & 206CCA are required to be complied by the deductor/ collectors of the tax on applicable transactions, which puts additional compliance burden on them. To provide remedy for the same, n ew functionality has been issued for compliance checks for section 206AB & 206CCA to ease compliance burden of tax deductors/collectors by the CBDT vide  Circular No. 11 of 2021 dt 21.06.2021 on implementation of section 206AB & 206CCA w.r.t. higher tax deduction/collection for certain non-filers. Please refer the copy of said circular enclosed hereunder: If you have any query related to the article please reach us via mail:-mrinkblog@gmail...

Form 15CA in excel format

Image
On 14th June, 2021 the CBDT has provided relaxation regarding submission of form 15CA & 15CB in manual format to authorised dealer till 30th June, 2021. In this reference, we are providing herewith copy of Form 15CA in Excel Format for making compliance easier. You can download the same by clicking the below given link: Form 15CA in Excel Format:  Click here Form 15CA in PDF as per ITD:  Click here Also, below is the link of our earlier article wherein we have provided update regarding the details of Press Relaese whereby such relaxation is provided: Press release details:  Click here If you have any query related to the article please reach us via mail:-mrinkblog@gmail.com  Advisory: Information relates to the law prevailing in the year of publication as indicated. The above article is only to enable public to have a quick and an easy understanding. Viewers are advised to ascertain the correct position/prevailing law before relying upon any document.

Relaxation in e-filing of Form 15CA and Form 15CB

Image
The CBDT in Press release issued today i.e., on 14/06/2021 has provided relaxation regarding e-filing of forms 15CA & 15CB. The same is reproduced hereunder: CBDT grants relaxation in electronic filing of forms 15CA & 15CB in view of difficulties reported by taxpayers in filing of forms online on the new e-filing portal https://incometax.gov.in. The forms can be submitted in manual format to the authorised dealers till 30th June, 2021.

Income tax due date extension_FY 2020-21

Image
On 20th May 2021 the CBDT vide its circular no. 09/2021 has extended various due dates for compliance under Income tax Act for the Financial Year 2020-21 (Assessment Year 2021-22), whereby among others, due dates for TDS return filing and SFT reporting have also been extended from 31st May 2021 to 30th June 2021.   Below is the link to download the press release in this regard: Press release_income tax Also, the copy of circular is provided hereunder for reference:

Section 194Q of the Income Tax Act - TDS on purchase of Goods

Image
   In the Finance Act 2021, the New Section 194Q has been inserted which reads as under: - '194Q. (1) Any person, being a buyer who is responsible for paying any sum to any resident (hereafter in this section referred to as the seller) for purchase of any goods of the value or aggregate of such value exceeding fifty lakh rupees in any previous year, shall, at the time of credit of such sum to the account of the seller or at the time of payment thereof by any mode, whichever is earlier, deduct an amount equal to 0.1 per cent of such sum exceeding fifty lakh rupees as income-tax.  Explanation: For the purposes of this sub-section, "buyer" means a person whose total sales, gross receipts or turnover from the business carried on by him exceed Rs. 10 crores during the financial year immediately preceding the financial year in which the purchase of goods is carried out, not being a person, as the Central Government may, by notification in the Official Gazette, specify for t...